

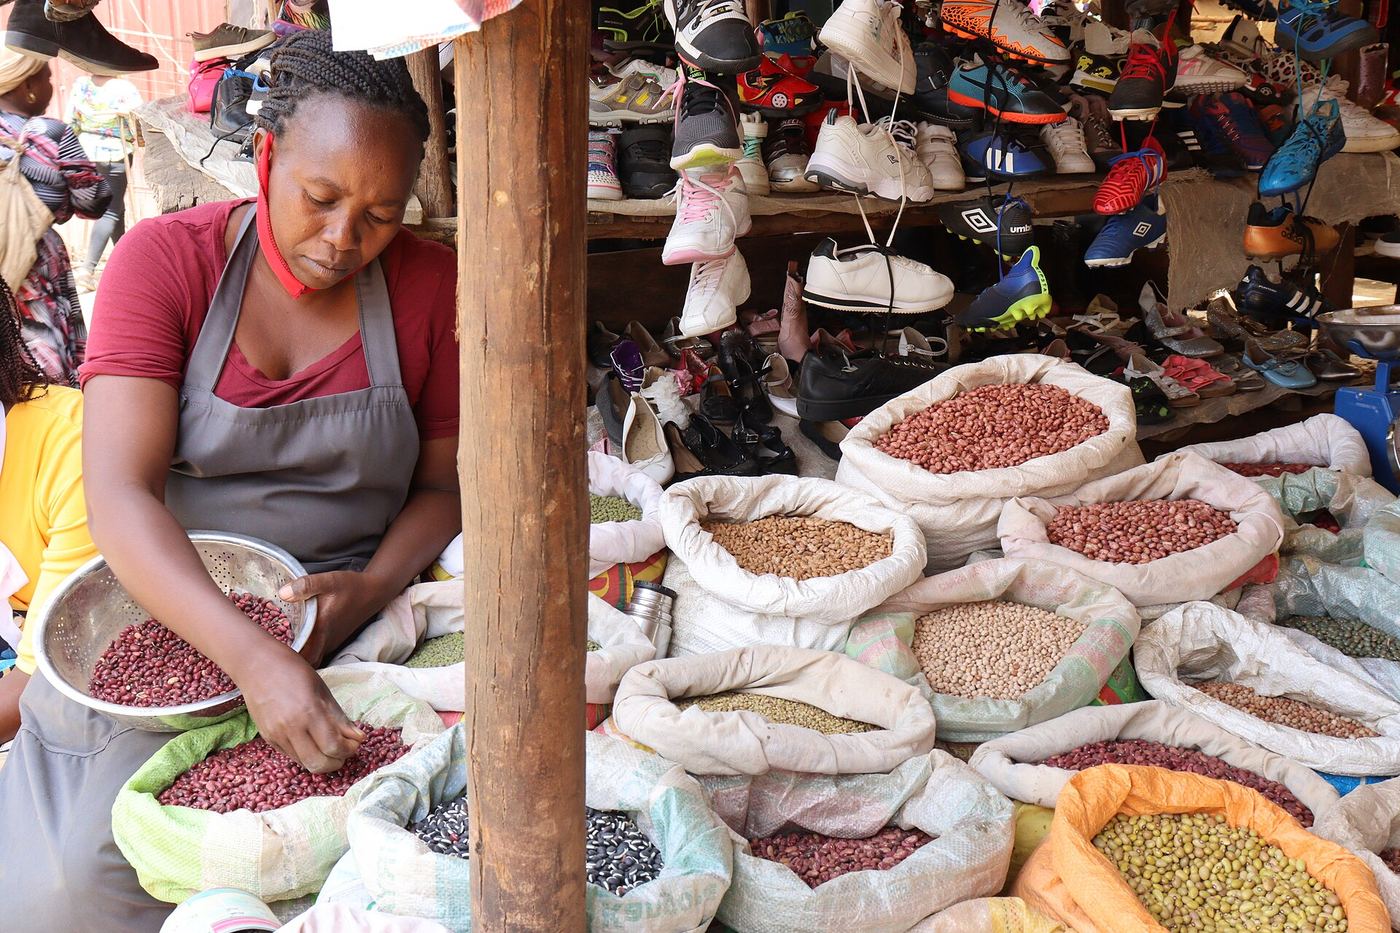
A vegetable seller in Indore, a tea stall outside a Patna station and a tailoring shop in Kochi now share something that would have seemed unlikely a decade ago: many of their customers pay by phone, in seconds, at no visible cost at the till. The Unified Payments Interface, run by the National Payments Corporation of India, has grown from a bank-led experiment into the default way much of India moves small sums of money, processing billions of transactions every month.
For large retailers, digital payments were an efficiency upgrade. For small merchants, they are closer to a change in how the business itself works — how money arrives, how records are kept and how credit becomes possible.
Cash Flow Without the Wait
Cash has hidden costs for a small shop: the risk of theft, trips to deposit notes, and the familiar problem of change for large denominations. A UPI payment settles into the merchant’s account almost instantly, which means the day’s takings can pay a supplier the same evening. Shopkeepers interviewed in market surveys repeatedly cite this speed, rather than novelty, as the reason they keep the QR code on the counter even when customers offer cash.
The Reserve Bank of India has supported this shift with its payments vision documents and the Payments Infrastructure Development Fund, which subsidised acceptance devices in smaller towns. Soundboxes that announce each payment aloud have also solved a practical problem in busy shops, letting staff confirm payment without handling the owner’s phone.
A Paper Trail That Can Unlock Credit
Perhaps the deepest change is invisible. A merchant whose income arrived entirely in cash had little documented proof of turnover when applying for a loan. Digital receipts create that record automatically. Lenders and fintech firms increasingly use consented transaction histories to underwrite small working-capital loans for shops that would previously have relied on informal moneylenders at far higher rates.
This does not make credit automatic or risk-free. Merchants still need to separate business and personal accounts, keep basic records and be wary of loan apps with unclear charges. But a verifiable stream of daily sales is a starting point that cash alone never provided. Our business coverage follows how banks and NBFCs are designing products around this data.
The Frictions That Remain
Growth has brought strains. Failed transactions during peak hours, fraud calls impersonating bank officials, and patchy connectivity in rural markets remain real problems. Merchant groups also continue to debate the economics of zero merchant discount rate on UPI, asking who pays for the infrastructure if not the accepting shop. Feature-phone users and those less comfortable with smartphones need assisted and offline options, several of which NPCI has been piloting.
Even with those caveats, the direction is clear. UPI has turned the mobile phone into a till, a ledger and, increasingly, a credit history for millions of small Indian businesses. The merchants who gain most will be those who treat the QR code not just as a payment sticker, but as the front door to formal finance — a theme we track in our finance section.
